Kathy Freeman Company | Executive Search | Investment Industry

Executive Search & Human Capital Consulting for Financial Services

  • Home
  • Firm
  • Searches
  • Insight
  • Contact

The Smart Approach to Executive Hiring in a Virtual World

Kathy Freeman Godfrey April 7, 2021


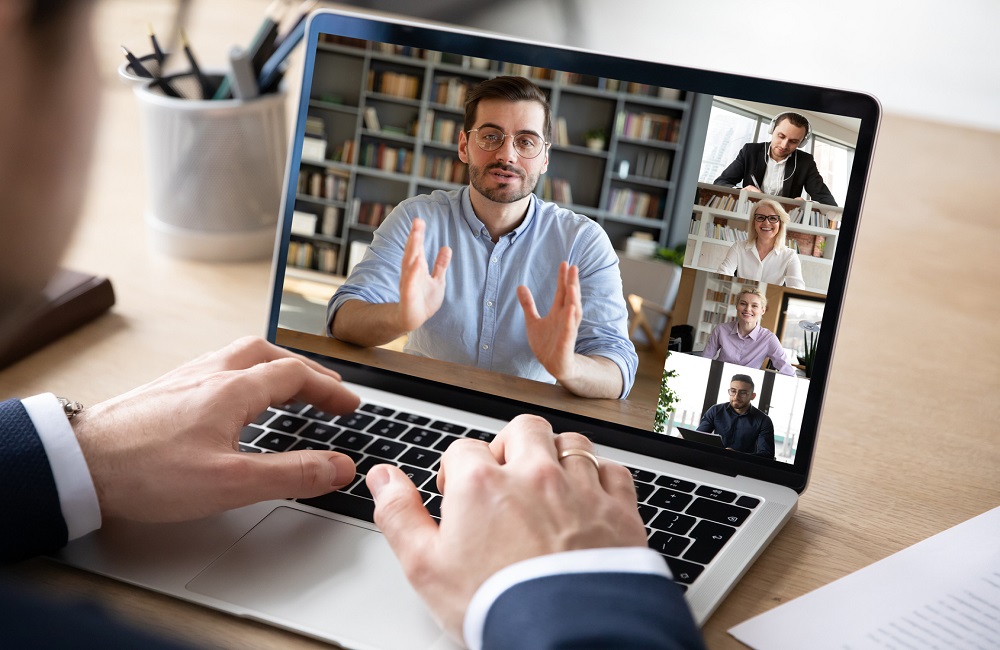
Companies across all industries have pivoted to virtual interviews since the pandemic began. Now 13 months into this grand experiment, the jury is still out regarding the effectiveness of solely relying on virtual interviews, especially at the executive level.

This new approach to hiring has also highlighted a new risk: Whether the virtual-only process works as well as the largely in-person, pre-pandemic approach. Here are three issues that are causing concern for our clients.

#1: Gauging A Candidate’s Real Interest Level

A key concern with virtual recruiting is determining how seriously a candidate is taking the interview process. Some companies that are solely hiring via virtual interviews, especially at the executive or leadership level, have been finding it challenging to assess whether a candidate’s interest is truly aligned with theirs. Some candidates are just kicking the tires from the convenience of home. It can be difficult to tell via video because visual cues and non-verbal communication, such as body language, aren’t as clear. Additionally, video interviews from home aren’t necessarily an accurate indicator of a high bar for interest. After all, another Zoom meeting is just part of the daily grind.

So, how does a hiring company know the interest is being reciprocated on the other side of the screen? How do firms protect the time of their leadership teams?

One of our clients worked around this challenge by creating to-dos for their executive-level candidates in parallel with their video conversations. After the preliminary or second round of interviews, they establish action items or tasks which require some level of preparation and commitment by the candidates. Those who weren’t that serious have bailed on the interview process. It’s better for everyone if a passive level of interest is discovered earlier in the process.

#2: Reducing the Number of Rejected Offers

An increase in rejected offers is another concern – one that is not an unexpected byproduct of virtual interviews. We suspect this is due to a lack of personal connection and difficulty building authentic rapport. In fact, some companies have been experiencing an increase in rejected offers as candidates take counter offers at their current companies. Some candidates are even leveraging offers as a negotiating tactic with other firms they are interviewing with. Now more than ever, rejected offers are highly disruptive to any hiring company’s momentum.

One response to this challenge is taking a more pointed and proactive approach with candidates. Don’t hesitate to ask if individuals are considering other opportunities and how far along they are in the process. Candidates, especially those who don’t interview often, may not realize that their transparency is valued and appreciated. If hiring companies are aware that a candidate is parallel processing other opportunities, they can be more aggressive in their pursuit of a candidate or be prepared to have backup candidates for consideration.

#3: Integrating WFH Executives Once Offices Reopen

Some clients are especially concerned about the cultural assimilation of executives who were hired virtually and have continued working from home. Many rightly wonder if and when a new hire will absorb the firm’s values and model that behavior. As a result, it’s more critical than ever that firms have a well-conceived executive onboarding plan for the post-WFH world.

Executive hires, who don’t typically need or expect nurturing, will be looking for confirmation that their new role is what they expected and that their new company is the right cultural fit. At the same time, everyone else will be checking to see if the new executive can rapidly assimilate, both culturally and influentially, in an office environment. Incorporating events that allow for team integration downstream will be equally as important.

Firms must embrace the cultural shifts that have occurred during the pandemic. The objective is to immerse new hires in the cultural values they are expected to exemplify when everyone returns to the office.

The Smart Approach aka The Hybrid Model

No one knows whether this experiment in virtual interviewing for executive-level hires will be successful in the long term. Only time will tell. In the interim, it’s prudent that companies transition to a hybrid interview model for executive roles if they haven’t already done so. As important is integrating and onboarding executives returning to the office, so they are culturally grounded and fully able to lead the growth of their companies in the months and years ahead.
Pandemic’s Impact On Human Capital & Executive Search At Family Offices, RIAs

Kathy Freeman Godfrey June 16, 2020


This commentary was published on June 12th, 2020 in Family Wealth Report.

The pandemic has forced leaders to reflect and modify their talent acquisition process and to prioritize retention. The author of this article drills into how COVID-19 affects multi-family offices and registered investment advisors.

Kathy Freeman Godfrey is president of Kathy Freeman Company, a national executive search firm working with multi-family offices and wealth management firms.

***

The COVID-19 pandemic has not only upended the financial markets, but it has also changed how family offices and RIAs will need to think through recruiting and managing talent in the months to come.

The pandemic has forced leaders to reflect and modify their talent acquisition process and to prioritize retention. The coronavirus has also prompted a discussion about what a firm’s future might look like given the health threat to the baby boomers who are leading many of these businesses.

Here are five key talent and executive search trends family offices and RIAs need to consider:

Succession planning has taken on increased importance.

COVID-19 has been a wake-up call for chief executives of multi-family offices and RIAs. Long considered an administrative chore, succession planning has risen to the top of the agenda because the pandemic has highlighted a number of strategic issues.

These include whether the firm has a viable strategy for long-term sustainability and whether that path leads it to remain independent or to sell.

As a result, CEOs have started thinking seriously about hiring a chief operating officer or a second-in-command. COVID-19 has swamped many CEOs with operational issues they should not, and prefer not, to handle. Professionalizing the leadership team by ensuring that the firm has a multi-dimensional and cross-talented leadership bench will support these seasoned leaders whether they choose to build a legacy organically or prefer M&A forlong-term growth.

Sophisticated client advisors and wealth strategists are in limited supply.

Client-facing talent is always in short supply, but even more so now. The complexity of working with the ultra-high net worth requires a much higher degree of technical competence than ever before.

Today, the CFP designation isn’t enough. Private client advisors and wealth strategists often have numerous advanced degrees or designations such as JDs, CPAs, LLMs, or CFAs. Professionals with this kind of advanced or niche expertise and accomplishments are in high demand. Beyond the technical competence, there’s a need to layer in a strong degree of EQ (emotional intelligence) to navigate conversations about complex issues with families and their heirs.

The interview timeline has been extended.

What used to be a fairly quick process for candidate interviews has now been stretching into months.Firms are integrating Zoom or Microsoft Teams to conduct video interviews, which has served as a good middle step for getting acquainted with potential candidates. However, with the importance of each and every hire, staffing decisions for critical roles are being postponed until face-to-face meetings can resume.

Employee retention efforts have become increasingly important.

Firms may be unaware that the downside to having employees working remotely is that there is a greater ability and willingness to take calls from search firms or recruiters. Management teams need to prioritize the engagement of talent, especially when we are living in this disconnected time.

If a firm is experiencing difficulties because of the pandemic, whether it is a liquidity issue or their inability to offer a compelling vision for the future, employees will sense these weaknesses and be more open to conversations from other firms.

Working remotely will impact the cultural paradigm of every firm.

This new remote working environment due to the pandemic is a unique opportunity to address work-life balance and strengthen employee loyalty.

Many employees have realized that they can be quite productive without water cooler distractions or lengthy daily commutes. However, other employees have dealt with tremendous challenges whether trying to teach their school-aged children or take care of their elderly parents all while trying to productively address their work responsibilities.

When firms begin to ask their employees back to the office, it needs to be done with an attention to retaining the best of the company’s culture, while allowing flexibility of working between home and office. Figuring out the best way to maintain a culture of growth, trust, and client excellence without the consistent office camaraderie is going to be a challenge which firms will need to address.

© Copyright 2020 ClearView Financial Media Ltd, 52 Grosvenor Gardens, London, SW1W 0AU, UK Tel: +44 (0) 207 148 0188 • info@clearviewpublishing.com • www.clearviewpublishing.com VAT Reg No: 843 3686 09 • Registered in England: 067841312

Gauging Your Own Professional Health – Time to Dig In or Pivot?

Kathy Freeman Godfrey December 12, 2019

Year end is a perfect time to reflect on your career.
Whether you are an individual contributor or in executive leadership, everyone struggles a bit to keep up with or stay ahead of the changes in the investment industry. One key takeaway from the hundreds of interviews we conducted this year is that some are happily evolving as the industry changes, while others are not enjoying themselves as much as they did.

My recommendation, for your “professional health,” is to make the time at year end to reflect on the work you are doing, who you are doing it for, and who you are working with. Then assess your satisfaction.

Understanding Yourself

In our interview assessments, we walk candidates through a series of questions many haven’t thought about in years. I wanted to share some basic but important questions for your consideration. Hopefully, you’ll create a better foundation from which to make future career decisions.

#1: Passion – What Do You Really Love About What You Do?

Your answer is exceptionally telling. Do you enjoy working directly with clients to solve their critical challenges? Do you enjoy working with a particular client segment? Do you enjoy building new businesses from scratch? Do you enjoy training and developing others? Are you the most energized in strategic roles or more tactical roles?

Take a moment to gauge your current passion for what you are doing. If it’s not high, consider the changes you need to make. Life is too short to spend time somewhere or doing something that doesn’t make you happy.

#2: Create Your Ideal Position Description.

This is a great exercise to step back from what you know and what you do each day. Consider the world from just your lens. Compare and contrast your existing role and firm to your ideal role and firm. Be sure to consider the responsibilities you enjoy most, the challenges you’d like to take on, and any new products or services you’d like to learn or represent in the market.

The investment industry is rapidly changing, which means people’s roles and firms are often in flux. Perhaps your responsibilities have increased, while others have been laid off. Although it’s good to be employed, if your workload is so great that other areas of your life are suffering, then something needs to change. Perhaps you don’t have a voice at the strategic table or it is being stifled. Or perhaps your firm isn’t innovating as quickly as other firms which is affecting your energy to champion your products or services. Considering the world from your ideal lens means asking tough questions of yourself, as well as reflecting on whether your company, its vision, and its trajectory are meeting your needs.

#3: Performance Matters. Be Aware of Your Own Bar And Pivot Your Career Accordingly.

It’s important that you have your own standards and are cognizant of where you are performing against your own bar. Since firms can, at times, set unrealistic expectations, it’s critical to have your personal benchmark to regularly reflect on your performance.

A good question to ask is how your performance measures up to those in a similar role. Are you differentiating yourself in any way? If so, how? If you don’t know or don’t care how you differentiate yourself from your colleagues, then you may be in jeopardy when layoffs occur. If you are underperforming, which happens to everyone at some time or another, then think through if there is a developmental opportunity you can identify to support your success. Don’t wait for someone to point out your failings. If you are exceeding against your own bar or your peers’, is there more you can do with your capabilities? Can you help others on your team achieve at a higher level? Would you like to be considered for a stretch assignment at your firm? Speak up! In preparation of stepping up, make the time to consider who you can train and pull up behind you to take your place.

Being self-aware is critical in this exercise. Identify your own performance benchmarks and where you measure on the scale. If you think you are exceeding your own expectations, congratulations! Now you can think more deeply about how you can be challenged further. If you have had a difficult year and aren’t quite where you’d like to be, consider what resources you need to achieve excellence again.

What’s Next?

Assessing your professional health is always a worthwhile endeavor, whether it is the end of the year or any time in between. If you feel like you have room to do more, commit to what “more” looks like and how to get there. If you’d like to do better, what are steps you can take toward improvement? If you’d like to do less, consider another role or firm that gives you that latitude.

Unemployment is at an all-time low. Great people are in short supply. Don’t settle for being less than happy. Pivot onto a better track.

Are You Guilty of Unconscious Bias? Five Ways to Build A More Equitable Workplace

Kathy Freeman Godfrey July 15, 2019

For over two decades, our work in the investment industry has allowed us to build wonderful relationships with exceptional people. However, we recognize much more progress on diversity is needed. The future success of the industry, which continues to be starved for top talent, will require the creation of a welcoming and inclusive culture in the workplace.
One key building block to inclusivity is eliminating or mitigating unconscious bias, which ultimately leads to unfair treatment of colleagues. Unconscious bias, or implicit bias, is often defined as prejudice or unsupported judgments in favor of or against an idea, person, or group.

Identifying Bias

What does bias in the investment industry look like? Here are a few recent, real-life illustrations from our industry colleagues:

  • A female CEO was in an all-male meeting when one executive who didn’t know her asked if she could get him a cup of coffee.
  • An impeccably dressed executive of color was attending a conference at a hotel and was misidentified by a guest as a hotel worker.
  • A female distribution executive was told she wouldn’t be the right fit for the promotion because she had a family and the new role involved a lot of travel.
  • A diversity wholesaler wasn’t asked to play an integral role in a firm’s diversity initiatives, which were being led by a team of middle-aged white men.
  • The sole female executive on her firm’s leadership team was repeatedly expected to be the note-taker during committee meetings.

Not only are these illustrations surprising to hear in a supposedly modern world, but this behavior sets back the cause of diversity in our industry and inhibits talented people from making a difference.

What to Do

To change the current dynamic, five simple steps need to be implemented to initiate change and create a more equitable workplace.

  1. Don’t assume. The examples above are based on outdated assumptions. They mistakenly reflect the fact that someone should have a particular skillset, role or responsibility because of their gender or color. To uncover bias, it’s useful to think about your own upbringing and have others on your team do the same. Examine your workplace assumptions about how things are or should be based on your firm’s legacy and history.
  2. Prioritize self-awareness. Make a weekly goal to observe and record situations involving unconscious bias. If you have stereotyped someone, record what you have done. Then, actively reflect on how to initiate positive change going forward.
  3. Speak up. If you witness bias by a colleague, take the individual aside and politely share your observations. Diplomatically suggest that this behavior is no longer acceptable. Alternatively, if you are in a room full of men who expect a female colleague to take notes, instead of calling out the bias, offer to take the notes yourself.
  4. Measure the diversity of your company, team, or colleagues. Because of the limitations of our own upbringings, we may not perceive bias. If you don’t have a diversity of backgrounds, experiences, ethnicities, or genders in your company or department, commit to change going forward.
  5. Recruitment strategies must address unconscious bias. One of the best ways to address unconscious bias is in the hiring process – before it is an issue. Educate your in-house recruiters or prioritize your executive search partners to ensure they understand unconscious bias and the importance of diversity and inclusion.

So, how does a woman become CEO if her colleagues assume she’s best suited for administrative tasks? How does a diversity sales professional make it to the leadership ranks if the individual isn’t asked to contribute to the conversation about diversifying the company’s sales teams? How can we assume that women can’t or won’t travel because they have a young family when we don’t assume the same for men?

Mitigating unconscious bias in the workplace is crucial. You may be unintentionally impeding the success of others, hampering an individual’s opportunity for career advancement, or inhibiting the investment industry from attracting a more diverse workforce. Let’s test the waters and commit to change!

Why EI and EQ Are Critical in Institutional Asset Management

Kathy Freeman Godfrey May 28, 2019

We recently participated in a roundtable discussion on the Evolution of the Institutional Asset Management Job Market hosted by Fundfire. One of the most interesting topics from that conversation was the need for greater Emotional Intelligence (EI) and a higher Emotional Quotient (EQ) to build successful client relationships with institutional clients.
We thought it might be helpful to elaborate on three key areas – empathy, self-awareness and gauging audience reaction – because each is so important today.

Empathy

An empathetic attitude makes your prospective or existing clients far more receptive to, and appreciative of, meeting with you. Today, your clients are asked to do far more with fewer resources, so their needs have become more extensive as their jobs have become more demanding. Coming armed to client meetings with thoughtful questions is a key way to demonstrate that you understand the more complex nature of their role. Frame those questions so your client has an opportunity to vent or de-stress with an ally instead of asking one-dimensional buying questions.

Self-Awareness

A deep knowledge of your own capabilities, as well an authentic, transparent and objective understanding of your firm’s offering, has become increasingly important. Simply suggesting how your offering might complement a client’s portfolio is insufficient. The sales process typically requires a richer, solutions-based discussion. Often, that means the ‘right’ answer you came into the meeting with won’t be relevant once you learn more about your client’s needs. Being self-aware can refocus the conversation on your client’s best interest and enable you to serve as a strategic advisor instead of a one-dimensional salesperson. With greater self-awareness, there is an opportunity to identify the best solution to suit your client’s needs as opposed to pointedly selling your strategy. The net effect: Long-term, quality relationships that lead to progressively more opportunities.

Gauging Audience Reaction

The art of successful client relationships is largely predicated on the strength of an individual’s interpersonal skills. As a result, accurately assessing your client’s communication style can make a huge difference in performance. A visual learner may find great benefit in a presentation. An analytical learner may prefer reports or spreadsheets. An auditory learner may simply want a phone call. Some clients like pithy, bite-sized updates. Others need to brainstorm or discuss ideas over big blocks of time. Introverted clients might open up more in a one-on-one lunch, while extroverted clients might be perfectly fine to meet in a social setting. Understanding your audience and calibrating your communication to your client’s preference is an art. Mastering that skill can’t be underestimated.

The Bottom Line

The growing competition in institutional asset management requires more than just technical investment proficiency or even the CFA® designation. Success happens when great investment expertise is complemented by a strong emotional intelligence and a high EQ. Reflect on your own EQ and gather feedback from colleagues and clients. It’s imperative to continually refine your approach to better serve your clients and more effectively earn the trust of prospects.

How Leadership Skill Sets in Asset Management Have Evolved

Kathy Freeman Godfrey April 25, 2019

I was recently interviewed by my good friend, Rob Shore, for his Wholesaler Masterminds Lessons From Leaders Podcast Series to share my perspective on how sales leadership requirements have evolved since the ‘90s and the critical traits wholesalers must possess today to be promoted into leadership roles in 2019.

First, we discussed highlights from our 10th Annual Talent Trends Report reflecting on the trends that stood out throughout the past decade.

Then, we discussed the evolution of sales managers over the years and exchanged insight on the essential skill sets for wholesalers looking to be promoted into leadership such as:

  • Authenticity – Caring for your team. No one cares about how much you know until they know how much you care.
  • Vision – Setting a vision, articulating that vision, and getting buy-in from your team.
  • Integrity – Being conscious of every decision that you make, and making better choices going forward.
  • Application & Articulation – Being able to articulate the science and foundation behind your own sales success.
  • Business Planning & Strategic Skills – Analyzing numbers and data from a strategic lens – not just a sales lens.
  • Innovation – Brainstorming on new ways to solve for certain issues such as increasing profitability.
  • Emotional Intelligence – Being an empathetic & self-aware leader.

Finally, we wrapped up with a quick discussion about various topics such as women and what they can do to migrate up the career ladder more effectively, consolidation, the importance of wholesalers to asset management, and the current talent shortage in the investment industry.

Listen to the entire podcast here, or check out the rest of Rob Shore’s Wholesaler Masterminds podcasts by visiting his website.

  • « Go to Previous Page
  • Go to page 1
  • Go to page 2
  • Go to page 3
  • Go to page 4
  • Go to page 5
  • Go to Next Page »

About Kathy Freeman Company

Kathy Freeman Company is a U.S. based strategic advisor to the investment industry and a national, retained, executive search firm. Named a Forbes Top 250 Executive Recruiting Firm in 2018 & 2019.

  • LinkedIn

KATHY FREEMAN COMPANY
805.542.0800


Menu

  • Home
  • Firm
  • Searches
  • Insight
  • Contact

White Papers

  • Talent Trends Report – Asset Management Leadership – January 2024
  • Talent Trends Report – Asset Management Leadership – December 2022
  • Talent Trends Report – Asset Management Leadership - 2021

Recent Blogs

  • Cultivating Talent That Thrives Amid Organizational Change
  • A Growth Mindset: The Ultimate Change Management Tool
  • Progress On Improving DEI, But Challenges Remain
  • Productivity: Its Heightened Importance Today In Asset Management Distribution

Copyright © 2026   Kathy Freeman Company